If you are selling in Tallahassee so you can buy on the Forgotten Coast, you are not making one move. You are managing two very different markets at the same time. That can feel exciting, but it can also get complicated fast when pricing, timing, taxes, insurance, and closing dates do not line up neatly. The good news is that with the right plan, you can protect your position on the sale side and buy on the coast with far more confidence. Let’s dive in.
Why this move needs a plan
Selling in Leon County and buying in places like Port St. Joe, Mexico Beach, or Cape San Blas means working with different market speeds and different purchase conditions. Over the last three months ending April 2026, Leon County homes sold at a median of $317,014 and spent a median of 63 days on market.
On the Forgotten Coast side, the numbers point to a different pace. Port St. Joe showed a median of $431,527 with homes going pending in around 99 days, Mexico Beach was at $449,268 in April 2026, and Cape San Blas had a median list price of $659,900 with a 71-day median market time and a buyer’s market designation.
That matters because your Tallahassee home sale may not line up perfectly with your coastal purchase. In practical terms, you may need more flexibility with your budget, closing date, or temporary housing plan than you first expect.
What the Tallahassee sale can mean for your coast purchase
Your sale in Tallahassee sets the tone for everything that follows. The amount you net, your closing timeline, and any contract terms you negotiate can directly affect what you can buy on the Forgotten Coast and how competitive your offer can be.
If you are relying on sale proceeds for your down payment, it is smart to build that into your purchase strategy early. Financing, contingency terms, and target closing dates should be planned together instead of treated like separate tasks.
Fannie Mae and consumer guidance both support getting preapproved early and understanding your options before you shop seriously. A preapproval helps you define your range, but it does not lock you into that lender.
Coastal timing is not always faster
Many buyers assume a slower coastal market means an easy or fast transaction. That is not always true. A property may sit longer, but insurance review, inspections, flood-zone questions, and financing details can still stretch the timeline.
In Port St. Joe, homes are described as not very competitive, with homes averaging about 4% below list. That can create room to negotiate, but it does not guarantee a quick path from contract to closing.
This is one reason a flexible contract structure matters. Depending on your situation, the right offer may need financing protection, inspection protection, or a closing date that works with your Tallahassee sale.
How Florida homestead affects your move
One of the biggest points of confusion in a Tallahassee-to-coast move is homestead. In Florida, homestead treatment is tied to your permanent residence, not a vacation home or second home.
That means you generally cannot keep homestead treatment on your Tallahassee home and also claim it on a coastal property unless the coastal home becomes your new primary residence. Florida law limits the benefit to one dwelling house.
It is also important to know that moving from one Florida homestead to another does not transfer the homestead exemption itself. What may be portable is the Save Our Homes assessment difference.
Know the portability deadlines
If you plan to make your Forgotten Coast home your new primary residence, timing matters. The new homestead must be established within three years of January 1 of the year the old homestead was abandoned.
To apply for portability, Form DR-501T must be filed along with Form DR-501 by March 1. Leon County and Gulf County both use a March 1 homestead filing deadline, and Leon County’s tax roll is based on the January 1 assessment date.
The key takeaway is simple: do not assume you can sort this out later. If your coast home will be your permanent residence, understand the January 1 residency test and file early.
Closing costs to remember in Florida
When you sell in Tallahassee and buy on the Forgotten Coast, you are dealing with closing costs on both sides of the move. One item many buyers and sellers overlook is Florida documentary stamp tax.
Florida applies documentary stamp tax to deeds and to mortgages or notes that transfer an interest in real property. That means this tax can affect both the sale of your Tallahassee home and the financing side of your coastal purchase.
Because these costs can change your cash-to-close picture, they should be part of your planning from the beginning. Knowing your likely net and your likely purchase costs helps you avoid last-minute surprises.
Flood zones should be checked early
On the Forgotten Coast, flood-zone review is not optional due diligence. FEMA’s Flood Map Service Center is the official public source for flood hazard maps, and flood risk can affect both financing and monthly ownership costs.
High-risk A and V zones can require flood insurance when you use a federally backed mortgage. Even outside high-risk zones, flood coverage is still worth serious attention because roughly 1 in 3 flood claims come from low- and moderate-risk areas.
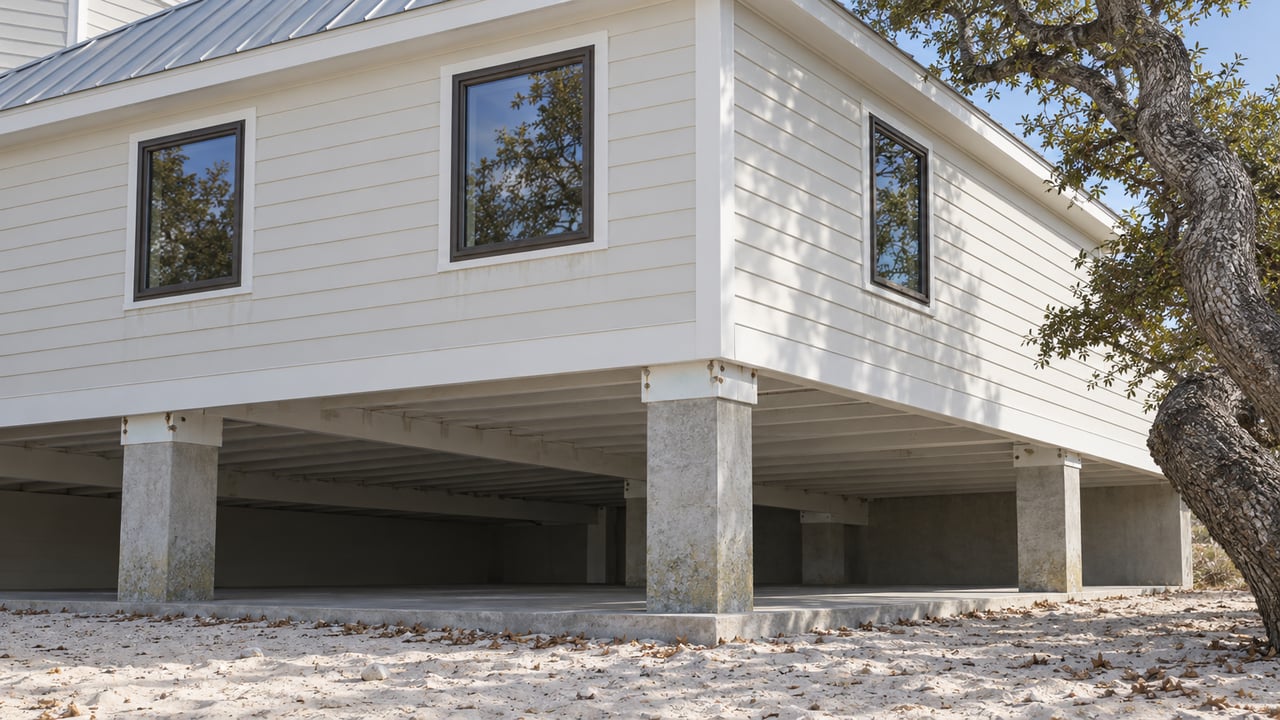
Before you commit to a property, verify the flood zone, ask how it may affect insurance, and factor that into your payment planning. This is especially important for barrier-island and near-shore homes.
Wind mitigation can change monthly costs
Insurance on the coast is about more than just flood coverage. Wind exposure, roof condition, opening protection, elevation, and deductible choices can all affect what you pay each month.
Florida requires insurers to offer wind-mitigation discounts, and the state allows the use of the official Uniform Mitigation Verification Inspection Form with a licensed inspector. That makes wind-mitigation features an important part of your due diligence.
Florida’s insurance guidance also notes that hurricane deductibles commonly include $500, 2%, 5%, or 10% of dwelling coverage, subject to some exceptions. A lower monthly premium may come with a much higher out-of-pocket risk after a storm, so quote comparisons matter.
Get insurance estimates before you finalize
For coastal buyers, insurance should be part of the shopping process, not an afterthought after inspections are done. Consumer guidance recommends getting an informal insurance estimate before committing to a higher-risk property.
That advice fits the Forgotten Coast especially well. A home that works on paper at the list price may feel very different once flood insurance, wind coverage, and hurricane deductibles are added to the monthly budget.
If you are comparing multiple coastal properties, compare the insurance picture too. Sometimes the better value is not the home with the lower purchase price, but the one with more manageable ownership costs.
Confirm how you plan to use the property
Before you write an offer, be clear about whether the Forgotten Coast home will be your primary residence, a second home, or an investment-style property. That distinction can affect financing and tax treatment.
Fannie Mae separates principal residences, second homes, and investment properties. Second homes must be occupied by the borrower for part of the year, be suitable for year-round occupancy, and generally cannot be rental property or a timeshare.
If you are thinking about occasional personal use, full-time living, or any short-term rental plan, confirm the intended use with your lender early. That can help you avoid financing issues later in the process.
Build the right team early
A move like this works best when everyone is aligned from the start. That usually means talking with multiple lenders early, getting preapproved, and coordinating your Tallahassee sale strategy with your coastal purchase plan.
It also helps to have a strong listing-side professional in Tallahassee and a local buyer’s agent on the Forgotten Coast who understands Port St. Joe, Mexico Beach, Cape San Blas, and nearby coastal inventory. Clear communication about representation, timing, inspections, and contract terms can save you stress.
Buyers can also often shop for some closing services, including title insurance and settlement services. When closing issues or legal questions come up, a settlement professional or attorney may also be useful.
A simple way to approach the move
If you want to reduce friction, keep your process in this order:
- Get clear on your Tallahassee sale price range and likely net proceeds.
- Meet with lenders early and secure preapproval.
- Decide whether the coast home will be a primary residence, second home, or investment-style purchase.
- Review likely flood and wind insurance costs before getting too far into negotiations.
- Structure offer terms and closing dates around your sale timeline.
- Plan ahead for homestead and portability deadlines if the coast property will become your permanent residence.
This kind of move is very doable, but it rewards preparation. The more you line up your numbers, timing, and property goals early, the smoother the transition can be.
If you are preparing to sell in Tallahassee and buy on the Forgotten Coast, you do not need a generic plan. You need local coastal guidance, clear timing strategy, and practical help connecting the sale side to the purchase side. The Burkett Team can help you navigate Port St. Joe and the surrounding Forgotten Coast with experienced, hands-on support.
FAQs
Can I keep my Tallahassee homestead if I buy on the Forgotten Coast?
- Usually no. Florida homestead treatment is generally tied to your permanent residence, so a coastal second home would not usually qualify unless it becomes your new primary residence.
What should I verify before making an offer on a Forgotten Coast home?
- Check the flood zone, possible flood-insurance requirement, wind-mitigation features, hurricane deductible structure, and whether the property use will be primary residence, second home, or investment.
How long do I have to apply for homestead portability in Florida?
- If you are moving from one Florida homestead to another, the new homestead must be established within three years of January 1 of the year the old homestead was abandoned, and the required forms must be filed by March 1.
Why does insurance matter so much for Forgotten Coast homes?
- Insurance can significantly affect your monthly cost because flood exposure, wind-mitigation features, roof condition, elevation, and hurricane deductible choices all play a role.
What professionals should I involve early in a Tallahassee-to-coast move?
- Start early with a lender, a Tallahassee listing professional, a Forgotten Coast buyer’s agent, and a title or settlement professional. If legal questions come up, an attorney may also help.
Is a slower Forgotten Coast market easier for buyers?
- Not always. You may have more room to negotiate on price, but inspections, insurance review, flood-zone research, and financing details can still make the process take time.